Quarterly returns
₹1,999+ GST ₹360 · per quarter
- TDS return in 24Q, 26Q or 27Q
- Challan matching before filing
- Form 16A downloaded and shared
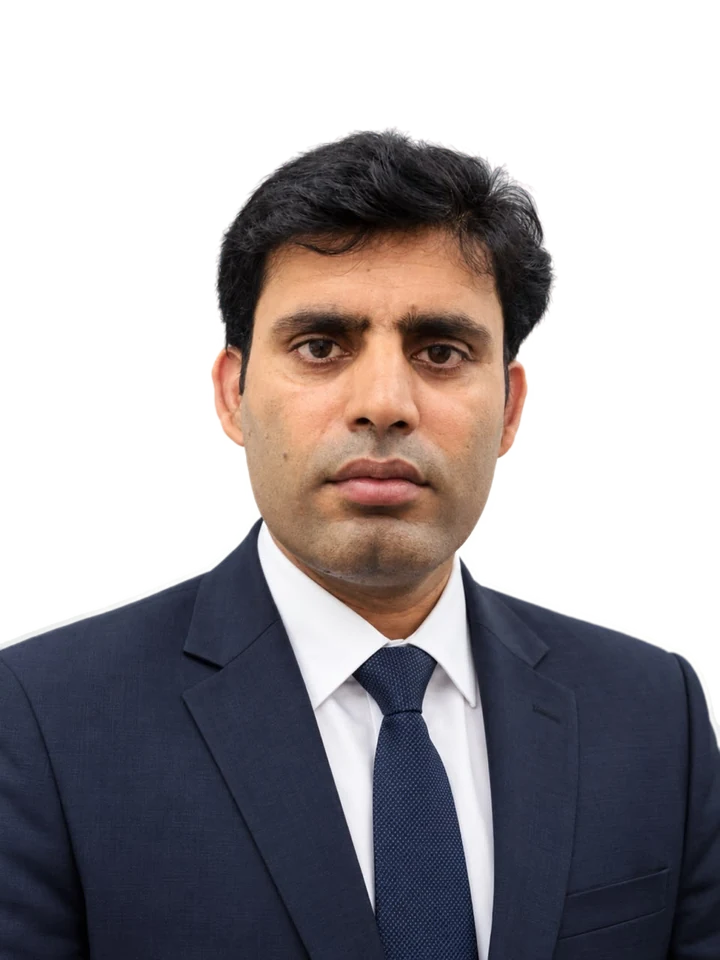
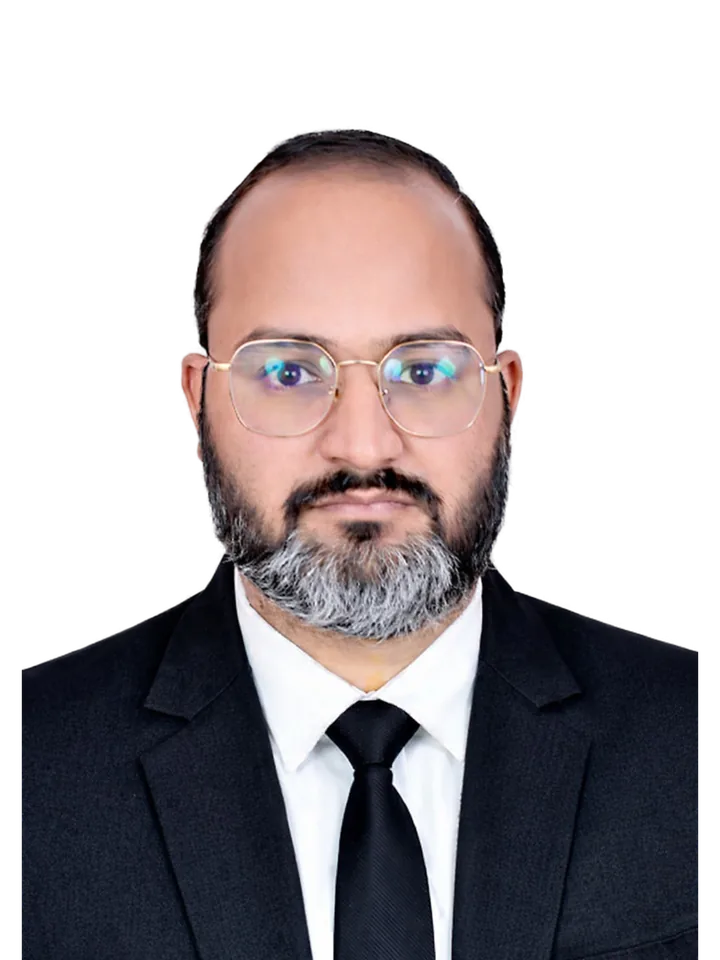
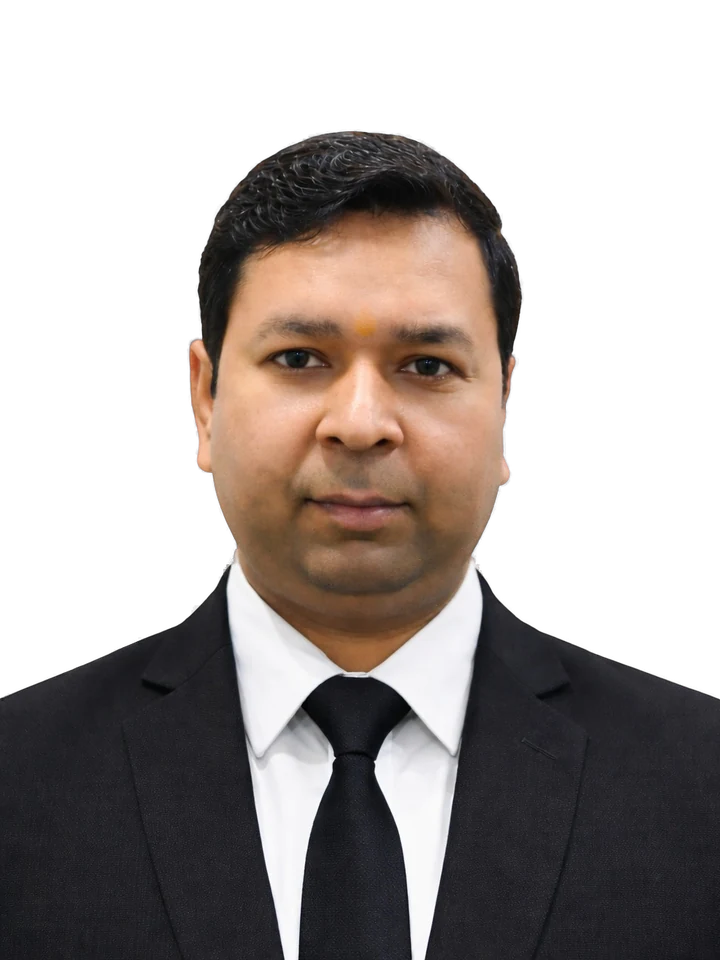 Company registration and brand protection expertsCS Prashant Kumar, CS Ashish Jain, CS Naresh Kumar Sharma · Fellow Company Secretaries · 40+ years combined
Tax deducted at source under the Income-tax Act
If your business deducts tax at source on salaries, rent, professional fees or contract payments, it must deposit that tax every month and file a TDS return every quarter. We compute the deductions, tell you what to deposit, and file the returns and certificates on time.
Choose by how much of the TDS cycle you want us to run.
Of the following month.
24Q, 26Q or 27Q.
Certificates for your payees.
Late fee for a late return.
Any business with a TAN that makes payments covered by TDS.
From the day you engage us, a named Company Secretary from this team is responsible for your TDS compliance: documents, filings, the department’s questions and the dates that follow.
A monthly deposit and a quarterly return.
Share payments made, with the payee’s PAN.
Works out the TDS and the amount to deposit.
Deposit the TDS through the challan.
Records the challan for the return.
Files the return and downloads Form 16A; Form 16 at year end.
Processes the return and flags any default.
Nothing here needs to be perfect; we check everything before filing.
| When | What | Law |
|---|---|---|
| 7th of next month | Deposit TDS deducted in the month (30 April for March) | Section 200; Rule 30 |
| 31 July | Return for April to June | Rule 31A |
| 31 October | Return for July to September | Rule 31A |
| 31 January | Return for October to December | Rule 31A |
| 31 May | Return for January to March | Rule 31A |
| 15 June | Form 16 to employees | Rule 31 |
Section numbers refer to the Income-tax Act, 1961, which governs returns for years up to 2025-26. The Income-tax Act, 2025 applies from tax year 2026-27, with new section numbers; dates are confirmed for each year, including any extension by CBDT.
Tax deducted is deposited every month; only the return is quarterly.
Section 200; Rule 30A late fee of ₹200 a day applies until the return is filed, up to the TDS amount.
Section 234E, Income-tax Act, 1961If the payee does not give a PAN, tax is generally deducted at a higher rate.
Section 206AA, Income-tax Act, 1961Correction statements can be filed to fix errors and clear defaults.
TRACES proceduresMany deduction obligations depend on audit status or the type of payment, not just size.
Chapter XVII-B, Income-tax Act, 1961The tax must also be deposited on time; deduction without deposit attracts interest and penalties.
Section 201, Income-tax Act, 1961Certificates must be issued to payees within the time allowed.
Section 203; Rule 31They apply only to the payer and amount stated, and must be checked.
Section 197, Income-tax Act, 1961The questions clients ask first, answered before you scroll.
By the 7th of the following month, and by 30 April for deductions made in March.
31 July, 31 October, 31 January and 31 May for the four quarters.
₹200 for each day of delay until the return is filed, up to the amount of TDS.
Yes. Form 16 for employees after the year and Form 16A after each quarter.
Yes. The default resolution engagement reviews the notices and files corrections.
You do, from your account. We compute the amount and share the challan details.
Founder, Startiqo · FCS (Fellow Company Secretary)
“Incorporation is your company’s first filing. My job is to set it up so every filing after it is easier.”
TDS defaults compound quietly: interest, late fees and disallowed expenses.
Get startedTo deposit TDS deducted.
Rule 30Late fee for a late return.
Section 234EEach year, one per quarter.
Rule 31AThe most common problems we see, and how we prevent them.
Credit does not reach the payee and defaults follow. We check PANs.
Interest and disallowance follow. We check rates.
Defaults appear on TRACES. We match before filing.
Payments abroad need 27Q and often 15CA/15CB.
Situations we see again and again, and how they are handled. No client is named or implied.
Starts monthly deposits and quarterly 24Q, with Form 16 at year end.
Default resolution files corrections and clears the record.
Deducts under the right section and files 27Q.
Plain-language reading, prepared for review by CS Prashant Kumar.
GSTR-1, GSTR-3B and the annual return, in plain language.
ReadAGM, AOC-4, MGT-7 and the dates that follow from them.
ReadFind pending filings before they become penalties.
ReadDownload, print and keep. Each guide is reviewed before it is published.
Deduction, deposit, returns and certificates.
Common payments and their sections.
Pick a plan; we keep every quarter on time.
Prepared for review by CS Prashant Kumar · Review date recorded on sign-off · Sources: Income-tax Act, 1961; Income-tax Rules; Income-tax Act, 2025