Nil filer
₹499+ GST ₹90 · per month
- Nil GSTR-1 and GSTR-3B filed
- Due-date reminders
- Annual return guidance
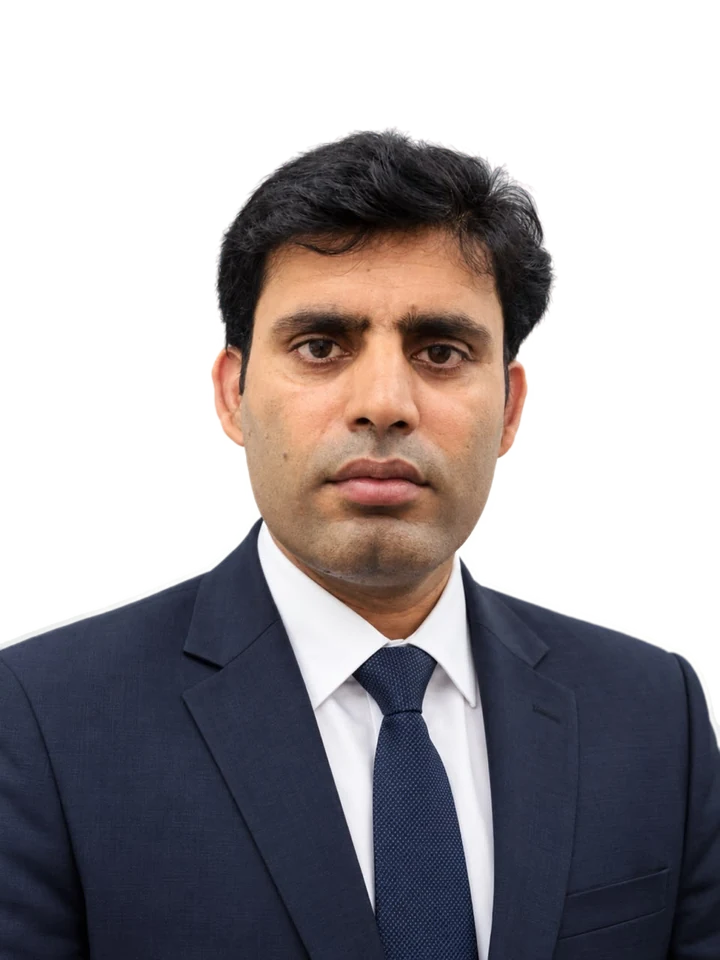
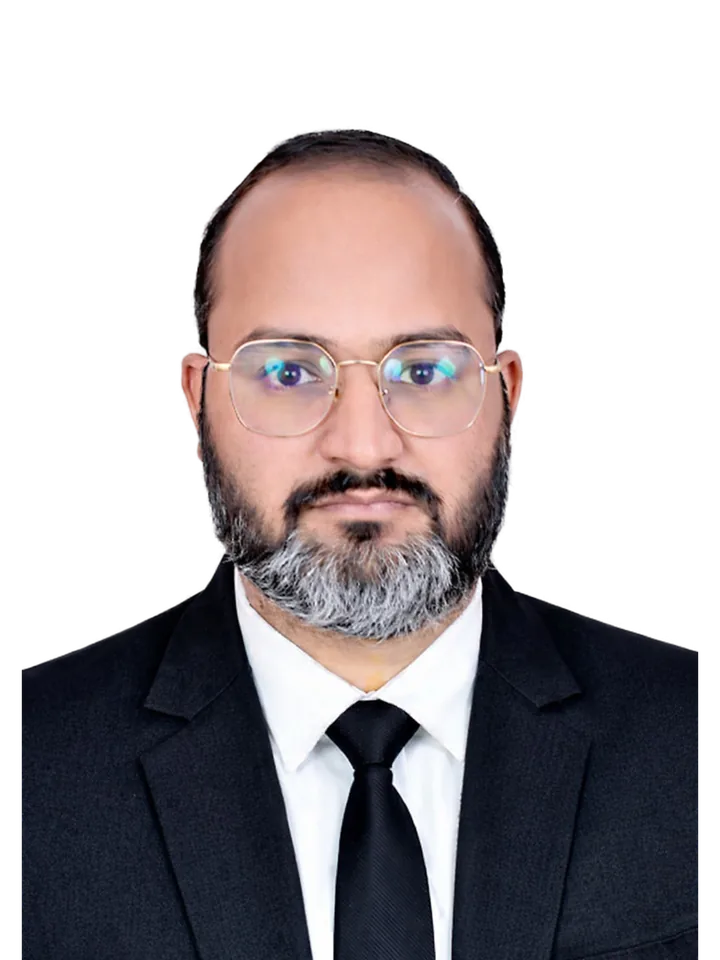
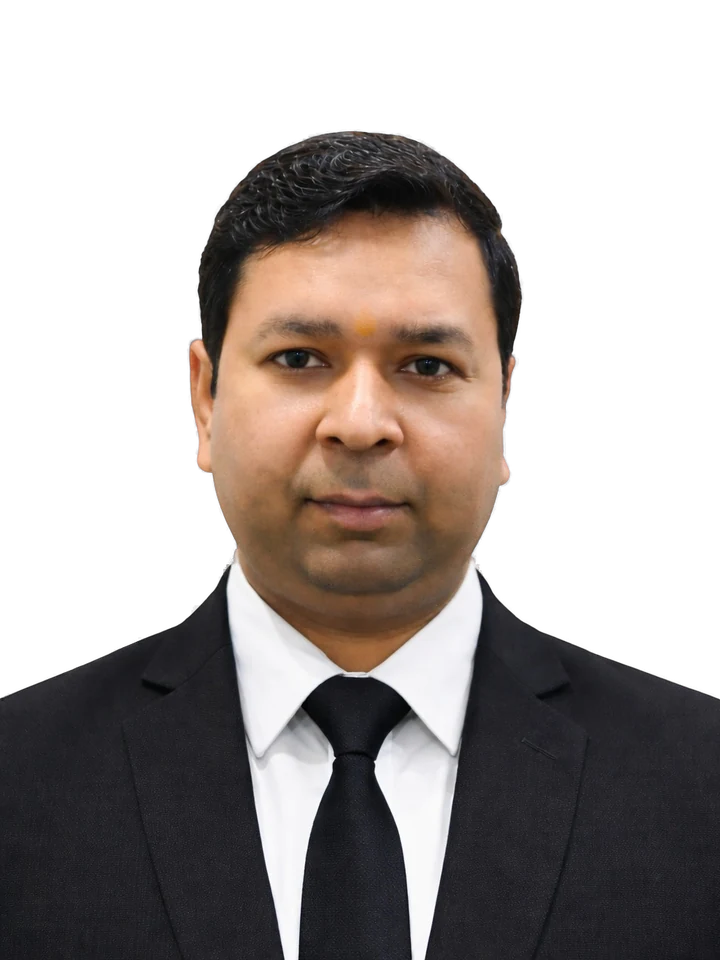 Company registration and brand protection expertsCS Prashant Kumar, CS Ashish Jain, CS Naresh Kumar Sharma · Fellow Company Secretaries · 40+ years combined
Returns under the Goods and Services Tax law
Every registered business files GST returns for every period, even when there are no sales. We reconcile your purchases with GSTR-2B before filing, tell you the tax payable before the due date, and file GSTR-1 and GSTR-3B on time.
Choose by how you file. Our fee and the GST on it are shown separately; the tax you owe the government is paid by you on the portal.
Annual return (GSTR-9) ₹1,999 and reconciliation statement (GSTR-9C) ₹1,999 are quoted separately.
Your sales, by the 11th for monthly filers.
Tax paid and summary, by the 20th.
File quarterly up to ₹5 crore turnover.
Purchases matched with GSTR-2B.
Anyone registered under GST, from the first period after registration.
From the day you engage us, a named Company Secretary from this team is responsible for your GST return filing: documents, filings, the department’s questions and the dates that follow.
A monthly cycle, with you sharing data and approving before anything is filed.
Upload sales invoices and the purchase register, or give us access to your accounting software.
Checks invoices for GSTIN, HSN and tax rates.
Reconciles purchases with GSTR-2B and computes the tax payable.
Approve the figures and pay the tax on the portal.
Files GSTR-1 and GSTR-3B and shares acknowledgements.
Records the filing and updates your ledger.
Nothing here needs to be perfect; we check everything before filing.
| When | What | Law |
|---|---|---|
| 11th of next month | GSTR-1 for monthly filers | Section 37 |
| 13th after the quarter | GSTR-1 for QRMP filers; IFF by the 13th of the first two months | Rule 59 |
| 20th of next month | GSTR-3B for monthly filers | Section 39 |
| 22nd or 24th after the quarter | GSTR-3B for QRMP filers, by state | Rule 61 |
| 25th of next month | Tax payment in PMT-06 for QRMP filers in the first two months | Rule 61A |
| 31 December | Annual return GSTR-9 for the previous year, where required | Section 44 |
Dates are as notified and can be extended by the government. We track every notification.
Every registered person files returns each period. Late nil returns still attract a late fee.
Sections 39 and 47, CGST Act, 2017Credit is available only where it is reflected in GSTR-2B and other conditions are met.
Section 16(2)(aa), CGST Act, 2017Under QRMP, returns are quarterly but tax is paid monthly.
Rule 61A, CGST Rules, 2017Late fees accrue daily and interest runs on unpaid tax; continued non-filing can lead to cancellation of registration.
Sections 29, 47 and 50, CGST Act, 2017Most taxpayers above ₹2 crore turnover must file GSTR-9.
Section 44, CGST Act, 2017; notificationsGSTR-3B cannot be revised; errors are corrected in later returns within the time allowed.
Section 39(9), CGST Act, 2017Credit for a year must be claimed within the time limit in the law.
Section 16(4), CGST Act, 2017Each return carries its own late fee until filed.
Section 47, CGST Act, 2017The questions clients ask first, answered before you scroll.
For monthly filers, GSTR-1 by the 11th and GSTR-3B by the 20th of the next month. QRMP filers file quarterly and pay monthly. Dates can be extended by notification.
You do, on the GST portal, from your own login. We compute the amount and tell you before the due date; it is never mixed with our fee.
You still file nil returns every period. Our nil-filer plan covers that.
If your turnover is up to ₹5 crore, you can opt for QRMP in the window the portal allows.
No. GSTR-9 and GSTR-9C are quoted separately because they depend on your turnover and records.
Yes. We review the last filed periods and the ledger before taking over.
Founder, Startiqo · FCS (Fellow Company Secretary)
“Incorporation is your company’s first filing. My job is to set it up so every filing after it is easier.”
GST penalises lateness every day. Credit lost through poor reconciliation cannot always be recovered later.
Get startedGSTR-3B for monthly filers.
Section 39Interest on tax paid late.
Section 50Turnover limit to opt for QRMP.
Rule 61AThe most common problems we see, and how we prevent them.
This credit is not allowed and leads to notices. We reconcile before filing.
Errors flow to buyers and cause disputes. We check each invoice.
Late fees build up daily even with no business.
Notices have deadlines. We track them in your dashboard.
Situations we see again and again, and how they are handled. No client is named or implied.
Opts for QRMP, pays tax monthly and files quarterly with reconciliation each time.
The mismatch report flags the missing credit early, and the trader follows up before filing.
Nil returns are filed on time, so no late fee builds up.
Plain-language reading, prepared for review by CS Prashant Kumar.
GSTR-1, GSTR-3B and the annual return, in plain language.
ReadThe MSME limits, the benefits and the free government portal.
ReadFind pending filings before they become penalties.
ReadDownload, print and keep. Each guide is reviewed before it is published.
Returns, dates, credit rules and late fees.
What to share with us each month.
Pick a plan and we file on time, every period.
Prepared for review by CS Prashant Kumar · Review date recorded on sign-off · Sources: Central Goods and Services Tax Act, 2017; CGST Rules, 2017; GST notifications