Notice reply
Fee to be announcedQuoted after a short review
- Review of the notice and your records
- Reply drafted and filed
- Hearing support where required
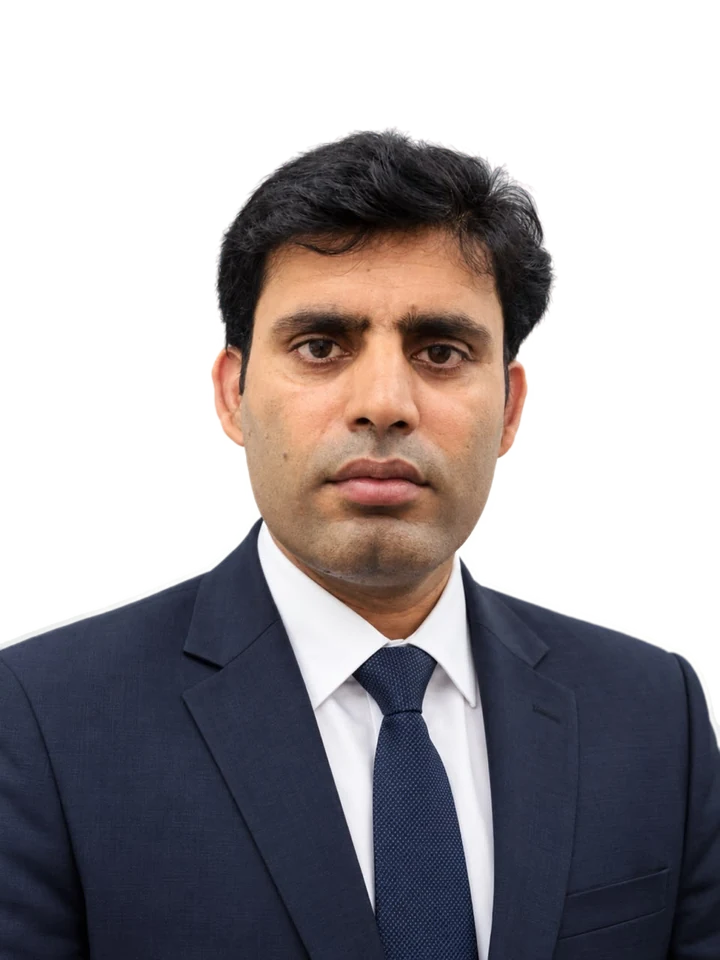
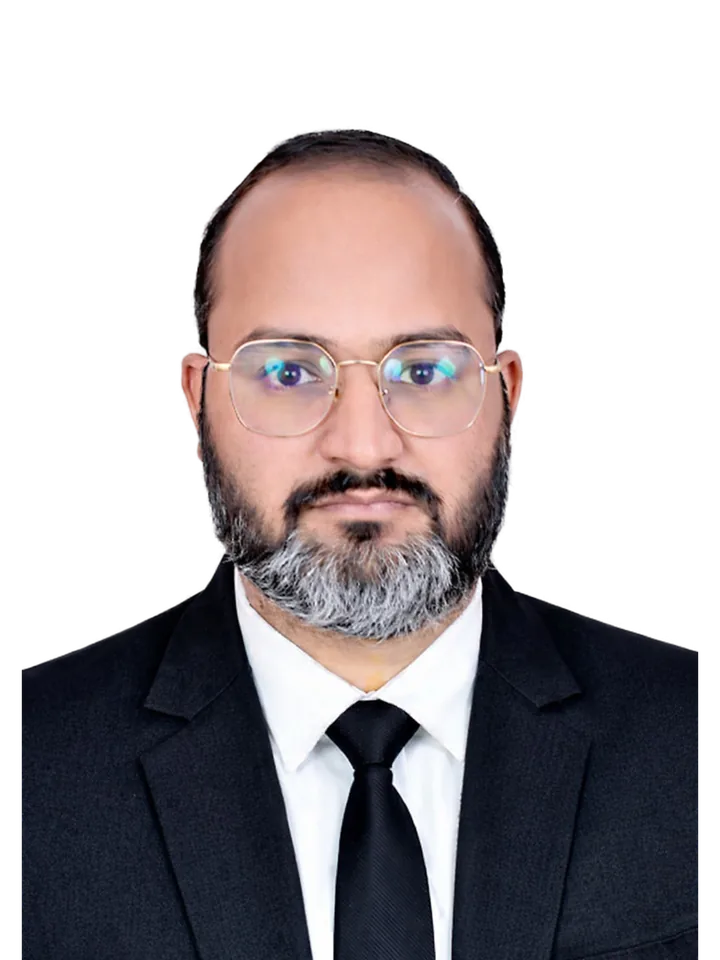
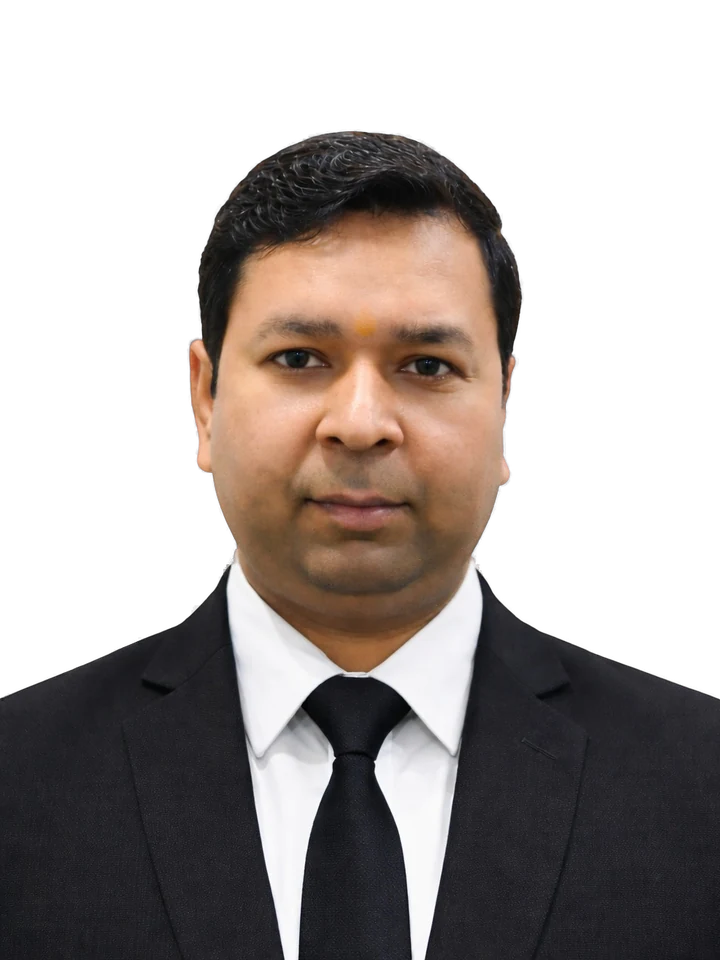 Company registration and brand protection expertsCS Prashant Kumar, CS Ashish Jain, CS Naresh Kumar Sharma · Fellow Company Secretaries · 40+ years combined
Advice under the Goods and Services Tax law
GST questions rarely fit a package. We review your position first, then quote for the specific work: replying to a notice, checking input tax credit, settling the classification or rate of a product, or making changes to your registration.
Where the work is standard, the fee is shown. Everything else is quoted after we see the facts.
Advance rulings, appeals and representation before appellate authorities are quoted separately.
Scrutiny and show cause notices.
ITC checked against GSTR-2B.
HSN and SAC settled in writing.
Scope and fee after a short review.
Businesses facing a decision or a notice.
From the day you engage us, a named Company Secretary from this team is responsible for your GST advisory: documents, filings, the department’s questions and the dates that follow.
Advice starts with facts. We review, scope and then act.
Send the notice or describe the issue.
Confirms the deadline and the documents we need.
Reviews the facts and sends a written scope and fee.
Approve and pay online.
Gives written advice or files the reply.
Accepts the reply or fixes a hearing.
Nothing here needs to be perfect; we check everything before filing.
An unanswered notice can lead to an order with tax, interest and penalty.
Sections 73 and 74, CGST Act, 2017Interest and, in some cases, penalty also apply, and a reply is still needed.
Sections 50 and 73, CGST Act, 2017Credit reversed for a supplier’s default can often be reclaimed once conditions are met.
Rule 37A, CGST Rules, 2017It binds only the applicant and the jurisdictional officer.
Section 103, CGST Act, 2017GST turns on facts. Advice should be written for your transactions.
CGST Act, 2017A summons requires attendance and evidence; it has its own procedure.
Section 70, CGST Act, 2017An appeal can be filed within the time allowed.
Section 107, CGST Act, 2017Replies drafted at the last minute are weaker. Start as soon as the notice arrives.
CGST Act, 2017The questions clients ask first, answered before you scroll.
After a short review of the facts or the notice, we send a written scope and fee before any work starts.
Yes, if the deadline allows. Send it as soon as you receive it.
We support you at hearings before the proper officer where our scope includes it. Appeals are quoted separately.
Yes. The GST health review covers credit, returns and reconciliations.
Yes, as a separate engagement after a review.
It is professional advice on GST for your facts, given in writing after review.
Founder, Startiqo · FCS (Fellow Company Secretary)
“Incorporation is your company’s first filing. My job is to set it up so every filing after it is easier.”
GST deadlines are strict. A missed reply can turn into an order.
Book a GST reviewTypical time to reply to a scrutiny notice.
Section 61; Rule 99Time limit for orders in non-fraud cases under section 73, counted as the law sets out.
Section 73Interest on tax paid late.
Section 50The most common problems we see, and how we prevent them.
Weak replies lead to orders. We prepare from the documents.
We record it on day one.
Some demands are not sustainable. We check first.
The same issue often affects other periods. We check them too.
Situations we see again and again, and how they are handled. No client is named or implied.
Mismatches are explained with invoices and the notice is closed.
Gets written classification advice before invoicing a new product.
Files the LUT so exports are made without paying IGST.
Plain-language reading, prepared for review by CS Prashant Kumar.
GSTR-1, GSTR-3B and the annual return, in plain language.
ReadFind pending filings before they become penalties.
ReadThe MSME limits, the benefits and the free government portal.
ReadDownload, print and keep. Each guide is reviewed before it is published.
Types of notice, deadlines and how to reply.
What to review before the year closes.
Send the question or the notice; we reply with a scope and a fee.
Prepared for review by CS Prashant Kumar · Review date recorded on sign-off · Sources: Central Goods and Services Tax Act, 2017; CGST Rules, 2017