Up to 10 employees
Fee to be announcedQuoted after a short review · per month
- Monthly payroll and payslips
- TDS on salary
- PF and ESI where applicable
- Professional tax where applicable
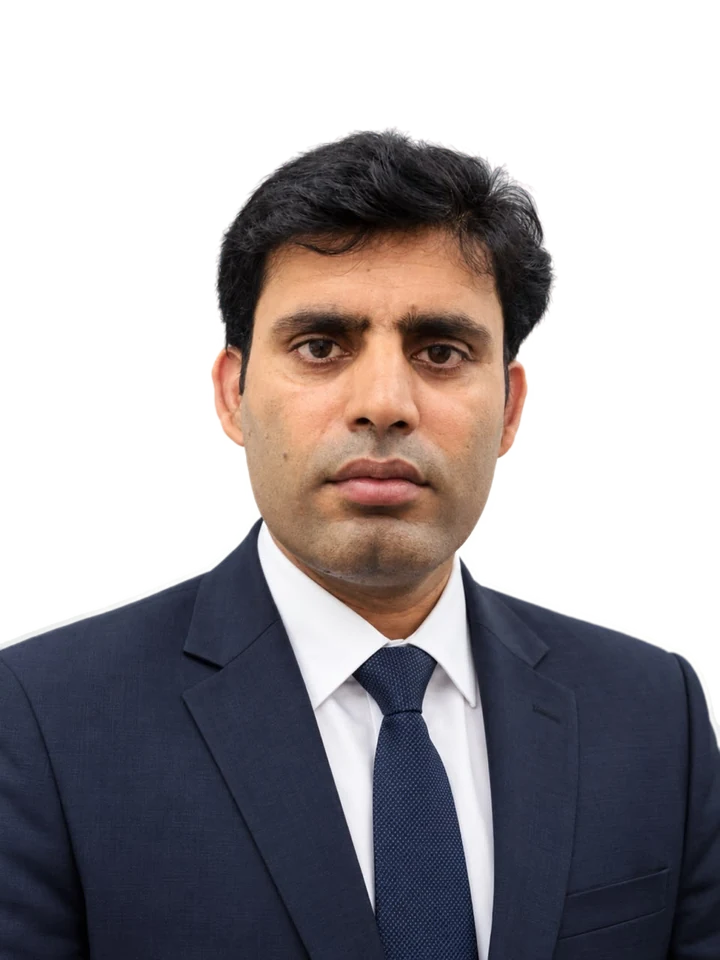
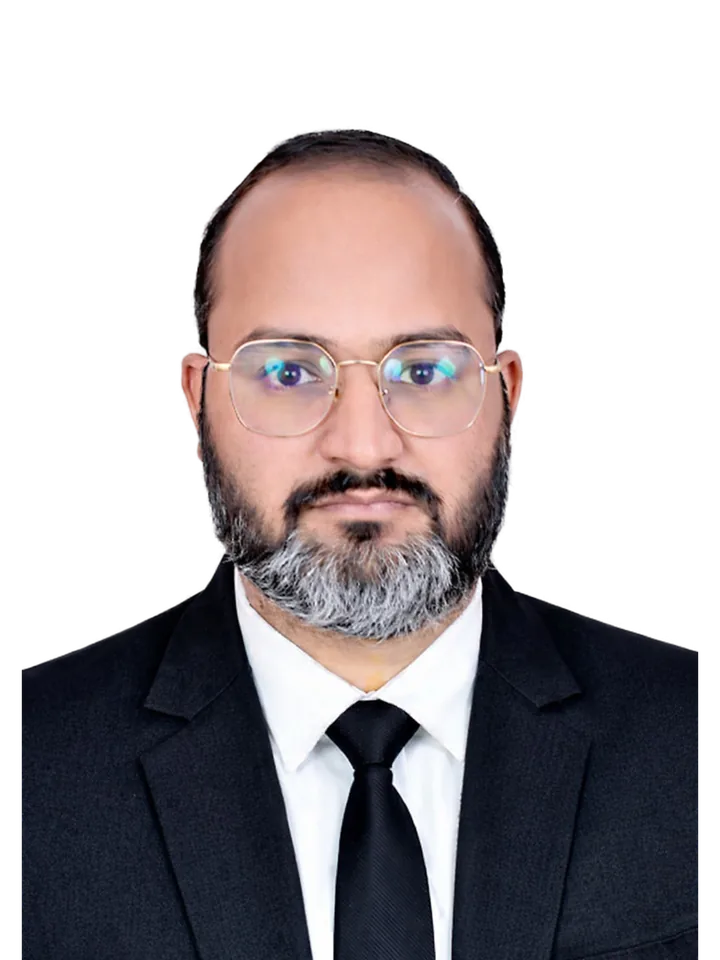
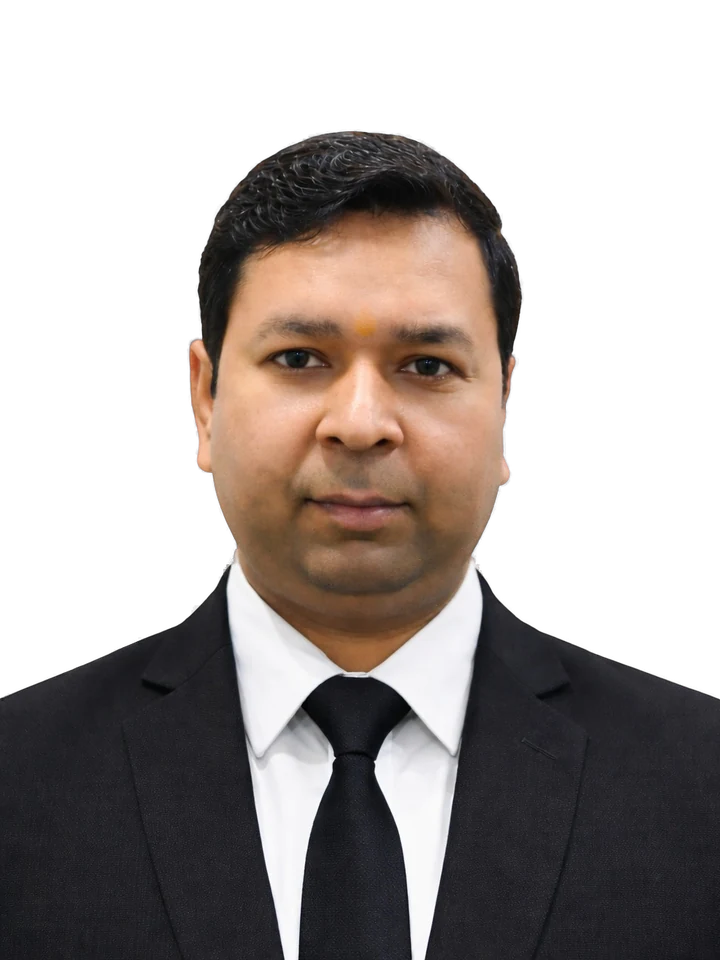 Company registration and brand protection expertsCS Prashant Kumar, CS Ashish Jain, CS Naresh Kumar Sharma · Fellow Company Secretaries · 40+ years combined
Salaries and statutory deductions
Payroll is more than paying salaries. Each month tax is deducted from salaries, PF and ESI contributions are paid where they apply, and professional tax is deducted in states that levy it. We run the monthly cycle, issue payslips and keep every deposit on time.
Plans are priced by headcount. Where no fee is published yet, ask for a quote.
Each month an employer computes salaries, deducts income tax at source under section 192 of the Income-tax Act, and deposits it with the government. Where the Employees’ Provident Funds and Miscellaneous Provisions Act applies, generally from 20 employees, PF contributions are deposited; where the ESI Act applies, generally from 10 employees, ESI contributions are deposited for employees within the wage ceiling.
Many states levy professional tax, deducted from salaries and paid to the state. The four Labour Codes notified by the Central Government consolidate several of these laws; we apply the provisions in force for your establishment when we process each month.
Source: Section 192, Income-tax Act, 1961; EPF and MP Act, 1952; ESI Act, 1948; state professional tax laws
Any business with employees.
From the day you engage us, a named Company Secretary from this team is responsible for your payroll: documents, filings, the department’s questions and the dates that follow.
A monthly cycle with your approval before salaries are paid.
Share joiners, leavers, attendance and changes.
Updates the payroll and checks the inputs.
Computes salaries and deductions and sends the register.
Approve and pay salaries.
Prepares TDS, PF, ESI and professional tax payments and returns.
Record the deposits and returns.
Nothing here needs to be perfect; we check everything before filing.
| When | What | Law |
|---|---|---|
| 7th of next month | Deposit TDS on salaries | Section 192; Rule 30 |
| 15th of next month | PF and ESI contributions and returns | EPF and ESI schemes |
| As set by the state | Professional tax deposit and return | State professional tax law |
| Quarterly | TDS return in Form 24Q | Rule 31A |
| 15 June | Form 16 to employees | Rule 31 |
Dates follow the applicable laws and can change by notification.
PF generally applies from 20 employees, and can be adopted voluntarily earlier.
EPF and MP Act, 1952Where the ESI Act applies, contributions are compulsory for employees within the wage ceiling.
ESI Act, 1948Tax is estimated and deducted every month across the year.
Section 192, Income-tax Act, 1961Only states that levy it; rates and dates differ by state.
State professional tax lawsWhether someone is an employee depends on the relationship, not the label.
Labour and tax lawsThe questions clients ask first, answered before you scroll.
By the number of employees and states. Where a plan shows no fee yet, ask for a quote.
No. You pay salaries from your bank. We compute them and give you the register and bank file.
Generally from 20 employees. We check when it applies to you.
Generally from 10 employees, for employees within the wage ceiling.
Yes, after the year ends.
Yes, including professional tax for each state.
Founder, Startiqo · FCS (Fellow Company Secretary)
“Incorporation is your company’s first filing. My job is to set it up so every filing after it is easier.”
Payroll errors affect your people first. Late deposits add interest and damages.
Ask for a quoteTo deposit TDS on salaries.
Rule 30For PF and ESI contributions.
EPF and ESI schemesFor Form 16 to employees.
Rule 31The most common problems we see, and how we prevent them.
Back contributions with interest. We check thresholds.
Shortfall at year end. We update declarations.
Penalties apply.
Disputes with leaving employees.
Situations we see again and again, and how they are handled. No client is named or implied.
PF registration and contributions start on time.
Professional tax is handled state by state.
Monthly payroll with reports for the parent.
Plain-language reading, prepared for review by CS Prashant Kumar.
AGM, AOC-4, MGT-7 and the dates that follow from them.
ReadFind pending filings before they become penalties.
ReadGSTR-1, GSTR-3B and the annual return, in plain language.
ReadDownload, print and keep. Each guide is reviewed before it is published.
TDS, PF, ESI and professional tax.
What to collect from each joiner.
Tell us your headcount; we run payroll every month.
Prepared for review by CS Prashant Kumar · Review date recorded on sign-off · Sources: Income-tax Act, 1961; EPF and MP Act, 1952; ESI Act, 1948; state professional tax laws