Annual filings
₹2,999+ GST ₹540
- AOC-4 with financial statements
- MGT-7 or MGT-7A annual return
- AGM notice and minutes
- MCA fees shown at actuals
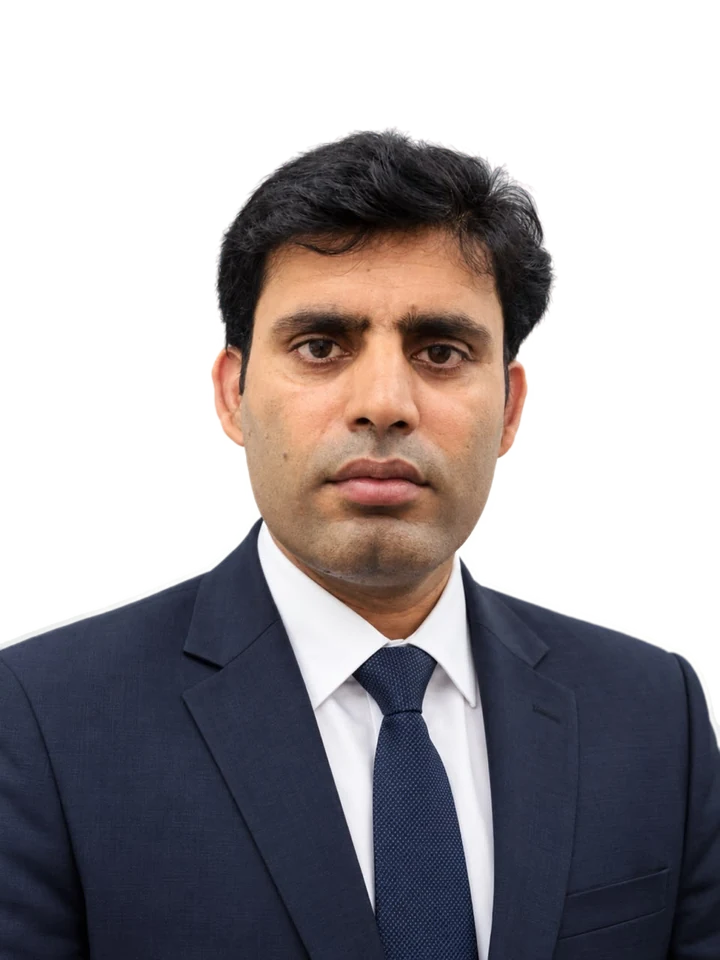
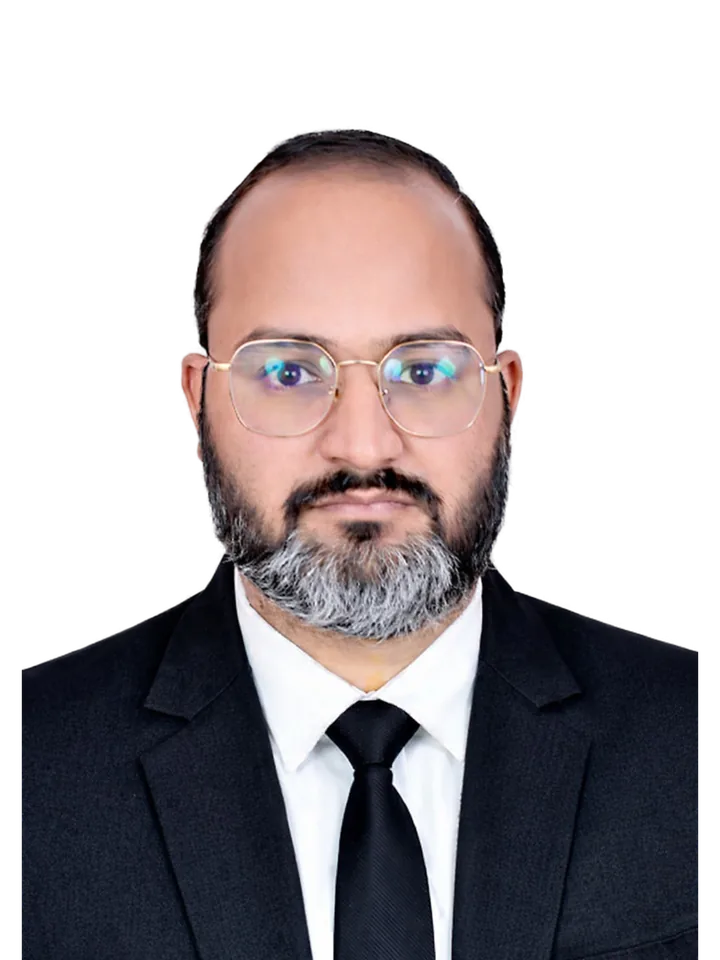
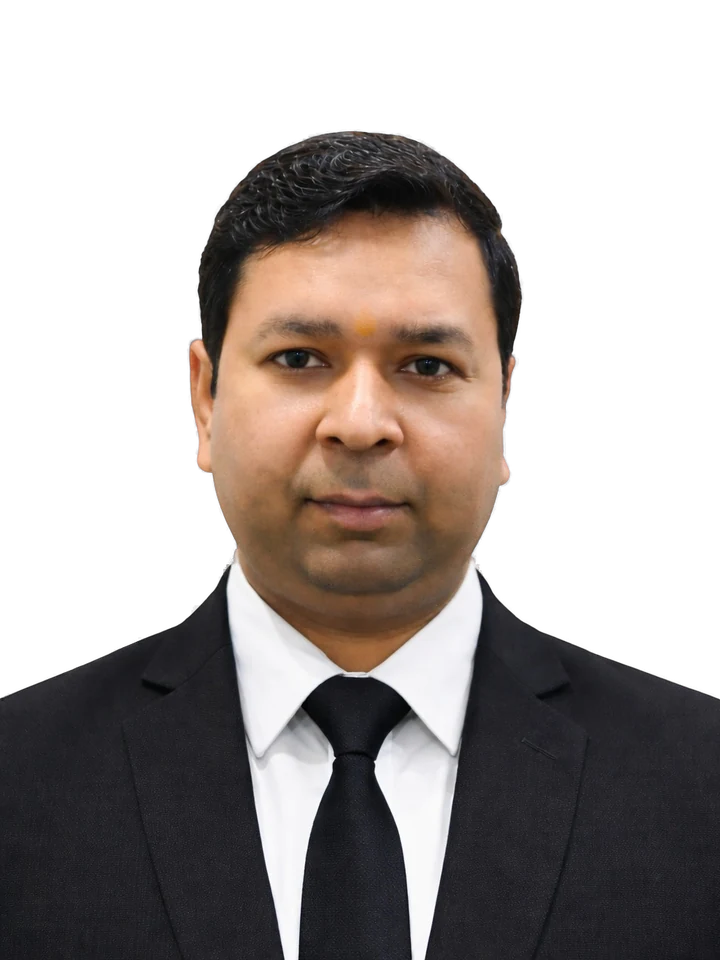 Company registration and brand protection expertsCS Prashant Kumar, CS Ashish Jain, CS Naresh Kumar Sharma · Fellow Company Secretaries · 40+ years combined
Annual filings with the Registrar of Companies
Every company files its financial statements and annual return with the Registrar every year, even with no business. We hold the meetings, prepare the documents and file each form on time, starting from your audited accounts.
Choose how much of the year’s company law work you want us to handle.
The statutory audit and income-tax return are separate. MCA filing fees depend on your capital and are paid at actuals.
Within six months of the year end.
Within 30 days of the AGM.
Within 60 days of the AGM.
Defaults can disqualify them.
Every company registered with MCA, whatever its size or activity.
From the day you engage us, a named Company Secretary from this team is responsible for your annual compliance: documents, filings, the department’s questions and the dates that follow.
From audited accounts to filed forms.
Share the audited financial statements and auditor’s report.
Checks them against the filing requirements.
Prepares the board report, notice and minutes for the board meeting and the AGM.
Hold the meetings and sign.
Files AOC-4, MGT-7 and the other forms due.
Approves the filings.
| When | What | Law |
|---|---|---|
| 30 April and 31 October | MSME-1, where payments to micro or small suppliers are due beyond 45 days | Section 405; MSME notification |
| 30 June | DPT-3 return of deposits and outstanding loans | Rule 16, Deposits Rules |
| Within 6 months of year end | Annual general meeting (by 30 September) | Section 96 |
| Within 15 days of the AGM | ADT-1 for the auditor’s appointment, where made | Section 139 |
| Within 30 days of the AGM | AOC-4 financial statements | Section 137 |
| Within 60 days of the AGM | MGT-7 or MGT-7A annual return | Section 92 |
Director KYC is filed as required under rule 12A. Dates can be extended by MCA; we track every circular.
Nothing here needs to be perfect; we check everything before filing.
Every company files AOC-4 and MGT-7 every year, even with no business.
Sections 92 and 137, Companies Act, 2013Additional fees of ₹100 a day apply to these forms, and penalties can follow.
Companies (Registration Offices and Fees) Rules, 2014Directors of a company that does not file for three years are disqualified.
Section 164(2), Companies Act, 2013Small companies and OPCs hold at least two a year.
Section 173(5), Companies Act, 2013Companies other than OPCs must hold an AGM.
Section 96, Companies Act, 2013The company files AOC-4 and MGT-7; the auditor signs the audit report.
Sections 92 and 137, Companies Act, 2013Accounts are audited every year.
Section 139, Companies Act, 2013It is also filed to report outstanding receipts not treated as deposits.
Rule 16, Companies (Acceptance of Deposits) Rules, 2014The questions clients ask first, answered before you scroll.
Yes. AOC-4 and MGT-7 are due every year.
Within six months of the end of the financial year, so by 30 September for a March year end. The first AGM is within nine months.
Additional fees of ₹100 a day for AOC-4 and MGT-7, and penalties can follow. Three years of defaults disqualify the directors.
No. The audit is done by your statutory auditor. We file after the audit.
No. MCA fees depend on capital and are paid at actuals, shown separately.
Yes. Compliance recovery covers pending years.
Founder, Startiqo · FCS (Fellow Company Secretary)
“Incorporation is your company’s first filing. My job is to set it up so every filing after it is easier.”
Missed annual filings can lead to director disqualification and, in time, the company being struck off.
Get startedAGM deadline for a March year end.
Section 96Additional fee for late AOC-4 and MGT-7.
Fees Rules, 2014Of defaults before directors are disqualified.
Section 164(2)The most common problems we see, and how we prevent them.
The AGM date drives everything; we plan backwards from it.
MGT-7A is for small companies and OPCs.
DINs are deactivated until KYC is filed.
A frequent gap for companies paying small suppliers late.
Situations we see again and again, and how they are handled. No client is named or implied.
Files nil-business financial statements and the annual return on time to avoid fees and disqualification.
Takes the Compliance plan so meetings and forms are on one calendar.
Starts with compliance recovery before the current year.
Plain-language reading, prepared for review by CS Prashant Kumar.
AGM, AOC-4, MGT-7 and the dates that follow from them.
ReadFind pending filings before they become penalties.
ReadName approval and trademark registration solve two different problems.
ReadDownload, print and keep. Each guide is reviewed before it is published.
Every filing, its form and its due date.
One page to print and keep.
Choose a plan; we keep every date.
Prepared for review by CS Prashant Kumar · Review date recorded on sign-off · Sources: Companies Act, 2013; Companies (Registration Offices and Fees) Rules, 2014; Companies (Acceptance of Deposits) Rules, 2014