Proprietor or professional
Fee to be announcedQuoted after a short review
- Return with business or professional income
- Presumptive or regular scheme reviewed
- Form 26AS and AIS checked
- Advance tax computation for next year
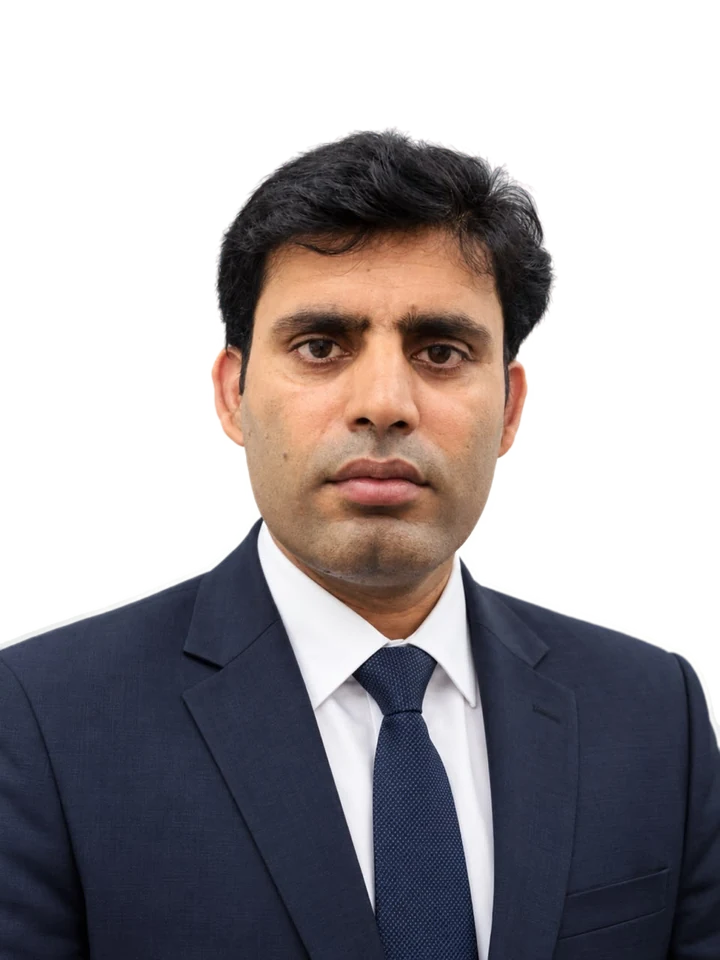
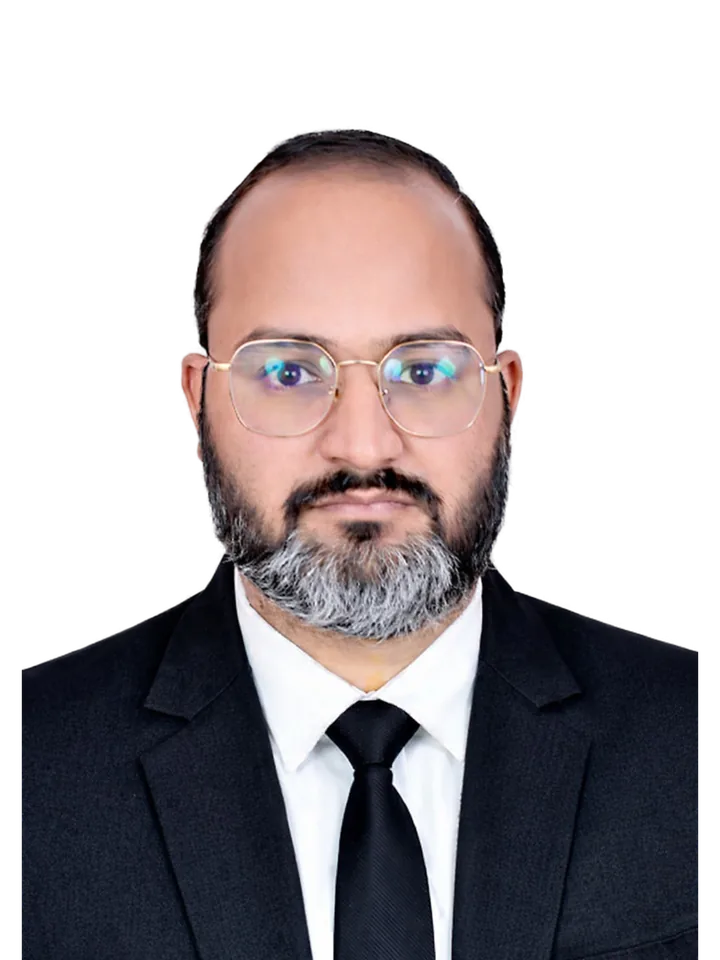
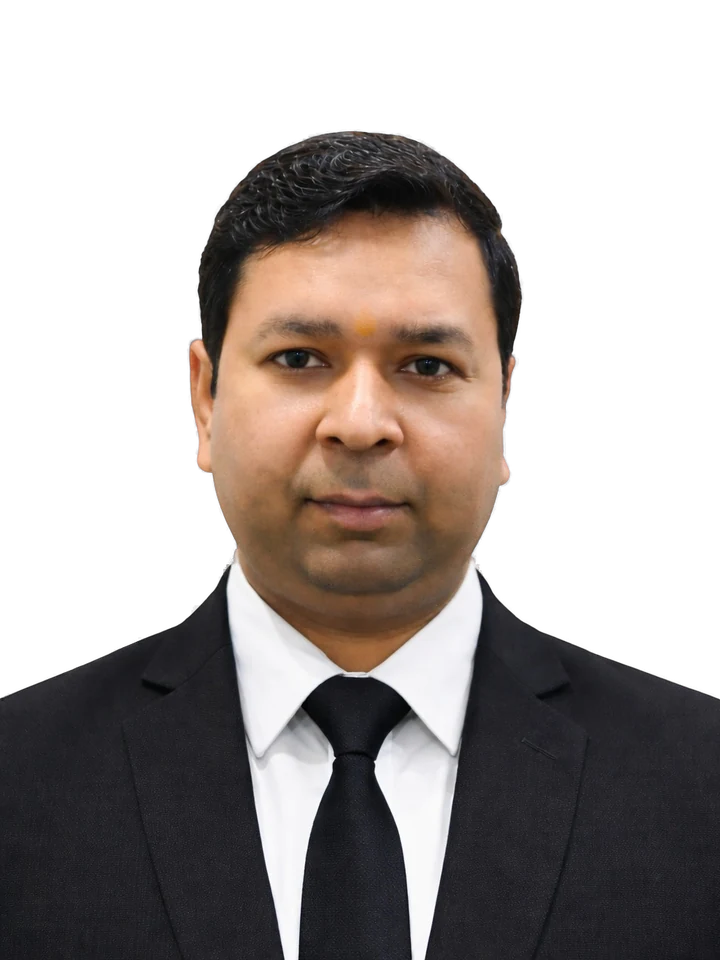 Company registration and brand protection expertsCS Prashant Kumar, CS Ashish Jain, CS Naresh Kumar Sharma · Fellow Company Secretaries · 40+ years combined
Returns under the Income-tax Act
Every company and LLP files an income-tax return each year, whether or not it made a profit. We prepare the return from your audited or finalised accounts, check tax deducted and advance tax against Form 26AS and the AIS, and file by the due date.
Choose by the kind of taxpayer. Audit, transfer pricing and notices are quoted separately.
Tax audit reports, transfer pricing reports and replies to notices are separate engagements.
Section 139(1) requires every company and LLP to file a return of income each year, whatever its income or loss. Proprietors and partners file when their income crosses the basic exemption limit or when other conditions apply. The return is filed electronically: companies with a digital signature, others with a digital signature or e-verification.
The return draws on your accounts, the tax deducted at source shown in Form 26AS, and the Annual Information Statement (AIS). Where accounts are audited under section 44AB or another law, the due date is later, and the audit report is filed before the return.
Source: Sections 139, 44AB and 234F, Income-tax Act, 1961
Every business entity, and owners with business income.
From the day you engage us, a named Company Secretary from this team is responsible for your income-tax return: documents, filings, the department’s questions and the dates that follow.
From finalised accounts to an acknowledged return.
Share finalised or audited accounts and bank statements.
Downloads Form 26AS and the AIS and lists anything that does not match.
Prepares the tax computation and the return.
Approve the computation and pay any balance tax.
Files the return and arranges verification.
Processes the return and issues an intimation.
Nothing here needs to be perfect; we check everything before filing.
| When | What | Law |
|---|---|---|
| 15 June, 15 Sept, 15 Dec, 15 March | Advance tax instalments | Section 211 |
| 31 July | Return where accounts are not audited | Section 139(1) |
| 30 September | Tax audit report, where required | Section 44AB |
| 31 October | Return for companies and audited taxpayers | Section 139(1) |
| 30 November | Return where a transfer pricing report is required | Section 139(1) |
| 31 December | Last date for a belated or revised return | Sections 139(4) and 139(5) |
Section numbers refer to the Income-tax Act, 1961, which governs returns for years up to 2025-26. The Income-tax Act, 2025 applies from tax year 2026-27, with new section numbers; dates are confirmed for each year, including any extension by CBDT.
Every company files a return every year, whatever its income or loss.
Section 139(1), Income-tax Act, 1961Business losses are carried forward only if the return is filed by the due date.
Section 80, Income-tax Act, 1961It is refunded only through a filed return, and only if it matches Form 26AS.
Sections 199 and 237, Income-tax Act, 1961A late fee also applies, and some deductions are lost.
Sections 234A and 234F, Income-tax Act, 1961The AIS covers businesses too, and differences must be explained.
Section 285BB, Income-tax Act, 1961The questions clients ask first, answered before you scroll.
Yes. Every company and LLP files a return every year.
31 July where accounts are not audited, 31 October for companies and audited taxpayers, and 30 November where a transfer pricing report is needed, unless extended.
No. A tax audit is done by a chartered accountant and quoted separately. We coordinate it with the return.
You pay it from your own account. We compute it and tell you the amount before filing.
We list the differences and help you follow up with the deductor before filing.
The Income-tax Act, 2025 applies from tax year 2026-27. Returns for earlier years follow the 1961 Act. We apply the right law for each year.
Founder, Startiqo · FCS (Fellow Company Secretary)
“Incorporation is your company’s first filing. My job is to set it up so every filing after it is easier.”
A late return can cost you the right to carry forward losses, not just a fee.
Get startedDue date for companies and audited taxpayers.
Section 139(1)For a return filed after the due date.
Section 234FOf advance tax each year.
Section 211The most common problems we see, and how we prevent them.
Differences can lead to notices. We reconcile before filing.
The loss cannot be carried forward. We plan the timeline.
Some regime choices are hard to reverse. We explain before you approve.
Interest applies for shortfalls. We give you a plan for next year.
Situations we see again and again, and how they are handled. No client is named or implied.
Files on time so the loss can be set off against future profits.
Reconciles Form 26AS and claims the refund in the return.
Reviews whether presumptive income suits the business before filing.
Plain-language reading, prepared for review by CS Prashant Kumar.
AGM, AOC-4, MGT-7 and the dates that follow from them.
ReadGSTR-1, GSTR-3B and the annual return, in plain language.
ReadFind pending filings before they become penalties.
ReadDownload, print and keep. Each guide is reviewed before it is published.
Forms, due dates and what to keep ready.
What to share before the return is prepared.
Pick your return type; we prepare and file it.
Prepared for review by CS Prashant Kumar · Review date recorded on sign-off · Sources: Income-tax Act, 1961; Income-tax Act, 2025; Income-tax Rules